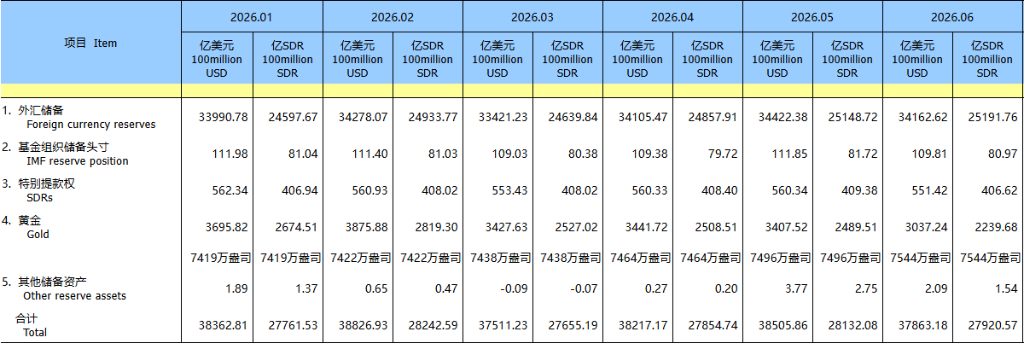
China’s gold reserves stood at 75.44 million troy ounces (approximately 2,346.446 metric tons) as of the end of June, an increase of 480,000 troy ounces (approximately 14.93 metric tons) from the previous month. Gold reserves at the end of May were reported at 74.96 million troy ounces (approximately 2,331.52 metric tons), marking the 20th consecutive month of gold reserve accumulation.
On July 7, data released by the State Administration of Foreign Exchange showed that China's foreign exchange reserves stood at USD 3.4163 trillion as of the end of June 2026, down USD 26 billion, or 0.75%, from the end of May.
The State Administration of Foreign Exchange stated that in June 2026, influenced by macroeconomic data from major economies, monetary policy decisions and expectations from key central banks, among other factors, the U.S. dollar index rose, while prices of major global financial assets exhibited mixed performance. The combined effects of exchange rate revaluation and changes in asset prices led to a decline in foreign exchange reserves for the month. China’s economy remains generally stable and is progressing toward higher-quality development, which supports the overall stability of foreign exchange reserves.
 According to data from the People’s Bank of China, China’s gold reserves stood at 75.44 million troy ounces (approximately 2,346.446 metric tons) as of the end of June, an increase of 480,000 troy ounces (approximately 14.93 metric tons) from May’s level of 74.96 million troy ounces (approximately 2,331.52 metric tons), marking the 20th consecutive month of gold reserve accumulation.
JPMorgan has revised down its Q3 gold price forecast to $4,300 per ounce and Q4 to $4,500 per ounce, representing a substantial 20%–25% reduction from prior expectations. This signals the end of the earlier 'blind bullish' phase, which was driven by safe-haven demand and aggressive central bank purchases.
Although gold prices have staged a technical rebound from around $4,000 per ounce, the bank explicitly cautions that near-term risks remain skewed to the downside—if summer economic data surprises with unexpected strength, forcing the Fed to hike rates earlier than anticipated, gold could break below $4,000, triggering technical selling and potentially testing the $3,500–$3,600 range.
Meanwhile, JPMorgan maintains its long-term bullish outlook on gold, expecting prices to resume an upward trajectory by 2027 as structural demand from central bank buying and physical investment returns, with an average annual price projected at $4,775 per ounce.
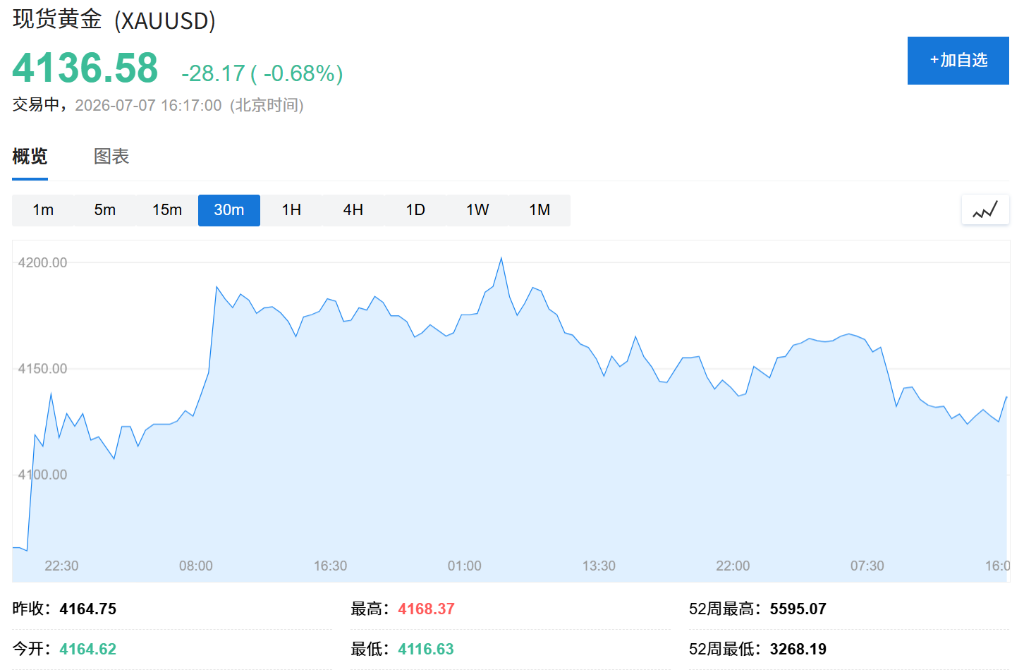
As of this writing, spot gold prices declined by 0.68% to USD 4,136.58.